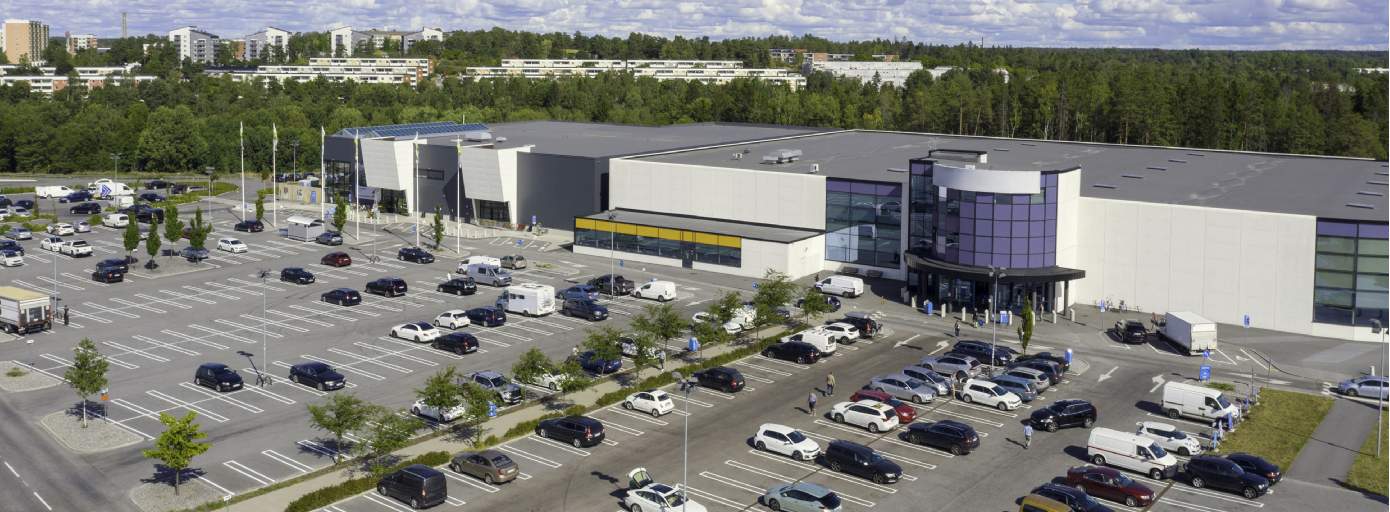
The greatest occupational endorsement comes from retailers’ sustained appetite for renewal and expansion.
Retail warehouses and parks have found favour with occupiers seeking relative occupational affordability and operational efficiency. In mature markets, the difficulty is often finding space. Availability sits below 3% in Ireland and 4% in the UK, while vacant units are often effectively non-existent in smaller Polish schemes. Considering such conditions, rental growth appears surprisingly subdued outside of Stockholm (Figure 13).
That apparent contradiction says much about the format. Part of the enduring appeal of out-of-town retail lies in its combination of affordability, accessibility and ample parking. For occupiers, that means the ability to trade at scale without compromising the value credentials on which many rely. Landlords are understandably wary of pushing rents to a point that weakens that advantage, even where space is scarce. In the most supply-constrained markets, low vacancy and churn can also limit evidence of prime rental growth. With few high-quality units becoming available, leasing activity can disproportionately concentrate within secondary stock, where rental ceilings are naturally lower.
Headline rents consequently capture only part of the income story. CPI-linked leases have continued to lift income across many European markets, including those where prime rents have barely moved. Thus, it is possible for passing rents to rise faster than prime estimated rental values, with indexation, retention and active management supporting growth within existing leases.
By geography, limited availability is creating rental tension in mature, supply-constrained markets such as Sweden and the UK. Across Central and Eastern Europe, Spain and France, new supply has provided more room for retailers to expand. This eases the pressure that strong occupier demand might otherwise place on rents. It is actually the behaviour of retailers themselves that constitutes the strongest endorsement. Occupiers continue to seek space, retain it and build out store networks around it; a weight of commitment which is hard to discern from rental growth alone.
Read the other articles within European Retail Warehousing below