Increasing rental prices across Copenhagen
Copenhagen housing rents are increasing rapidly. Over the past two decades, sustained housing demand has consistently outstripped supply, applying continuous upward pressure on rent levels – a trend that persisted through the global financial crisis and the more recent inflationary crisis. Following the “Blackstone” legislative reform in 2020, which among other changes removed the materiality criterion in rent tribunal proceedings, the section 19.2 rent level for older multifamily properties recorded a decline.
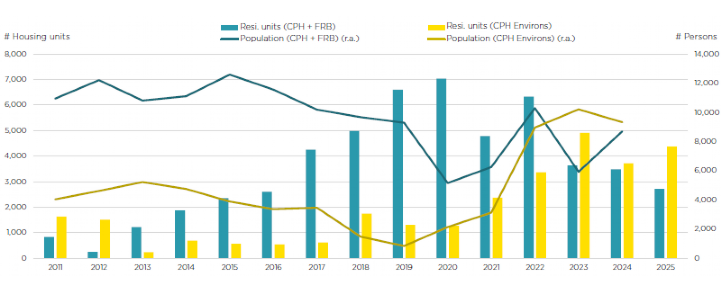
Over the past 18–24 months, rental growth has accelerated further within the residential new-build segment in Copenhagen, coinciding with a marked slowdown in project completions and the corresponding absorption of newly delivered stock. The change is reflected in submarkets such as Ørestad, where the average annual churn rate has been reduced by roughly half over the last 18 months, and now sits well below 20%. While household income growth imposes a natural ceiling on rent escalation, the combination of continued in-migration and rising household incomes supports further rent increases.
The strongest rental growth has been observed among smaller flats, which command the lowest nominal rents. In the most desirable central Copenhagen districts, smaller units now achieve rents around 3,300 DKK/sqm/year, while comparable units in the Copenhagen environs achieve approximately 2,500 DKK/sqm/year. The smaller rental flats attract robust demand from younger tenants, students, and newcomers to the city, which pushes demand upwards. This dynamic also underscores that tenants who prioritise location over unit size demonstrate a higher willingness to pay, sustaining strong pricing resilience in compact formats.
Rapid growth in owner-occupier values
Since early 2023, average owner-occupier flat prices in Copenhagen have increased by an impressive 63%. The strongest value growth has been recorded in Frederiksberg, Copenhagen K and other central city districts along with waterfront locations. For select residential assets on absolute prime locations, this sharp rise underscores the significant value potential for properties with a feasible break-up strategy – a trend increasingly reflected in investor pricing.