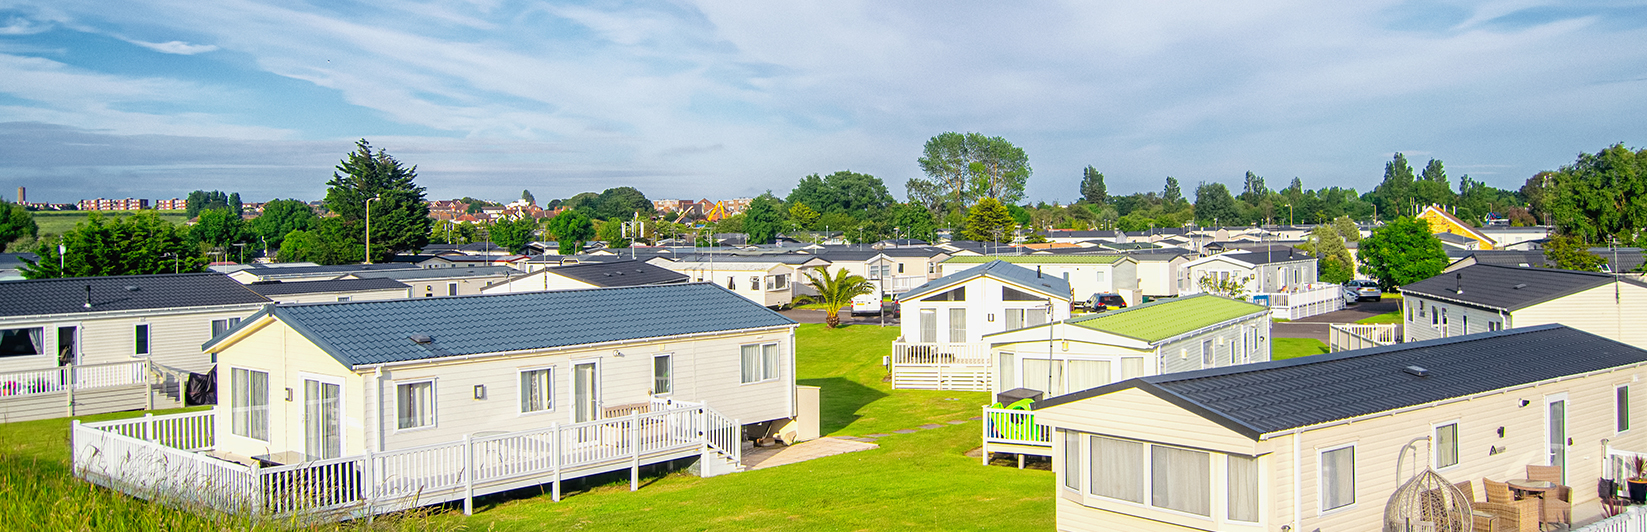
Holiday parks prospered in 2021 whilst other industries have suffered. Due to the pandemic, holiday parks have benefitted from increased demand for both the purchase of holiday homes and the letting of holiday units. Without exception, park owners are reporting above average occupancy levels and demand for the purchase of new units (subject to the availability of caravan stock).
The current market conditions have been described as the perfect storm to drive values upwards. However, investors have been keeping a watchful eye on this market and it is perhaps the disruption experienced in the traditional investments of hospitality and retail that have made holiday parks so appealing.
Caravan parks have been going through somewhat of a metamorphosis and a shift in customer base. Many operators are reporting that holiday parks are now appealing to higher socio-economic groups than previously, resulting in many park owners making significant improvements to park facilities and offering a better quality of holiday accommodation such as ‘luxury lodges’. This improved perception of holiday parks is perhaps one of the contributing factors bringing new investors to the marketplace and assisting with the strongest market conditions the sector has ever encountered.
A Confidential Marketplace
Market intelligence remains difficult to obtain due to the confidential nature of holiday park transactions. Most transactions are either off market or to a closed audience. Understandably a sales process can disrupt the on-going business and as such it has now become standard practice to avoid the open market where possible. The data collated over 2021 has been collected from accurate transactional sources and predominantly parks sold by Savills.
Private Equity
The sector has changed dramatically with the influx of private equity on a large scale. This has driven investment into parks improving standards, releasing capital for further development and instead of being a short term shift due to staycations, we see this as a long term shift in the sector, akin to investors going into hotels or healthcare or student accommodation in previous years.
The headlines for 2021 have been dominated by private equity resulting in the highest level of group transactions of holiday parks recorded in any one year. Holiday parks have become a chosen investment for private equity due to their resilience and ability for potential future growth, all of which has been compounded by the lack of performance from private equity’s traditional targets such as retail and hospitality.
Private equity investors aggressively seek growth from their investments and the recent activity will likely result in a flurry of further transactions as groups continue to bolster their portfolios exciting the market further.
Forecast for 2022
Holiday parks continue to attract a multitude of investors who have come to appreciate the model. The holiday park market is now evolving more quickly than it has done previously giving consumers greater choice and ensuring the future of the industry. It is with little doubt that Savills predict that 2022 will be another strong year for holiday parks and premiums will continue to be paid for large holiday parks in good locations.
Whilst the high prices currently being paid for large holiday parks may not be attributable to smaller and regional parks, we are seeing something of a trickle down effect as smaller parks up their game in terms of standards. As a result, the income achieved and strong competition at higher levels is pushing some regional operators to consider smaller offerings with development potential to acquire in order to achieve expansion. We therefore may see the market firming for smaller sites also.