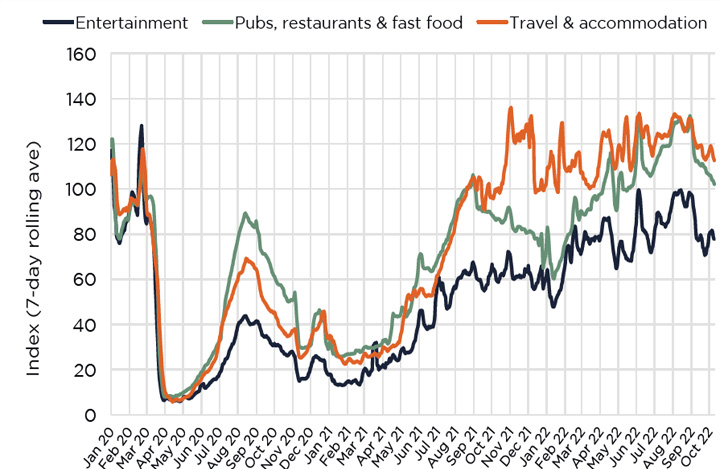
The first half of 2022 generally saw robust trading conditions for pubs, with many operators reporting a bounce back in trade and like for like sales above pre-Covid 2019 levels. At the same time there has been a gradual improvement in city centre trade due to the partial return of office workers and younger customers being attracted back to the buzz of urban nightlife - albeit still below prepandemic levels.
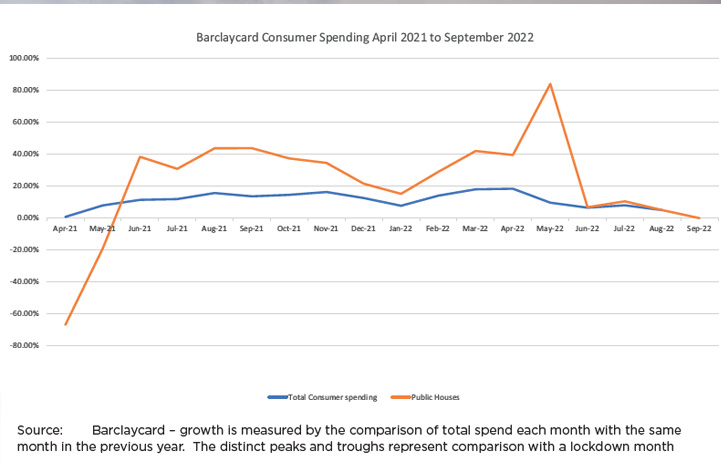
Barclaycard reports that consumer spending in pubs contracted by 0.4% in September 2022 compared with September 2021. The graph below compares monthly consumer spending in pubs against total consumer spending from the initial reopening of hospitality in April 2021 to date. The data shows that the spend in pubs has outperformed the total consumer spend since June 2021 showing the resilience of the sector. It is only since June this year that spending in pubs has mirrored or slightly outperformed total consumer spending.
Despite the post-Covid recovery in sales, the sector is facing significant operating cost headwinds. Increases in labour costs have already had an effect on operating margins. However, as a consequence of the Ukraine/ Russia conflict, energy, transport and fuel costs are all set to have an impact in the second half of this year and well into 2023 and beyond.
The full effect of energy price rises is starting to be felt in the pub market and given wider inflationary pressures operators have sought to pass on some of the operating costs to customers through higher prices, tightened cost control and adapted menus where possible.