UK commercial property investment volumes rose 10% year on year in Q1 2020 to £12.7 billion, compared to Q1 2019, with some sharp rises in investment into some retail segments before Covid-19 affected the markets, according to the latest research from Savills.
In its April Commercial Market in Minutes report the international real estate advisor says there is very little evidence of “post lock down” pricing in the UK market yet. According to Savills, while the yield hardening it was predicting in some sub-markets, such as City of London offices, is now on hold, any yield softening is unlikely to mimic that seen in the Global Financial Crisis as the general level of indebtedness across the sector is significantly lower than it was in 2006/7, although there may be further bank-led sales of retail assets given the underlying structural issues in the sector. At the moment, however, Savills UK average prime yield for commercial property remains stable at 5.04%.
Mat Oakley, head of UK and European commercial research, says: “The current view amongst many forecasters is a very sharp downturn in GDP growth followed by an equally sharp upturn from Q3 - a relatively short and severe shock in economic terms. In our opinion this is very much a best-case scenario, as it rules out a second wave of infections as well as underplaying the sheer scale of the Governmental response to the current crisis. While monetary policy measures such dropping the BoE base rate to 0.1% and announcing £200 billion of asset purchases could be argued as not having a minimal hangover effect, the fiscal stimulus measures announced in recent weeks such as tax cuts and deferrals, general public spending increases and more targeted welfare transfers will result in borrowing more or spending less in the future. Furthermore, while most measures have been presented as time-limited, nobody currently knows when they will be able to be withdrawn.
“A combination of longer lock downs, a secondary surge in infections, and the fiscal measures that have been put in place could result in the recovery being less steep than the downturn, although even under this scenario both the economy and property market will be back to normal levels by mid-2021.”
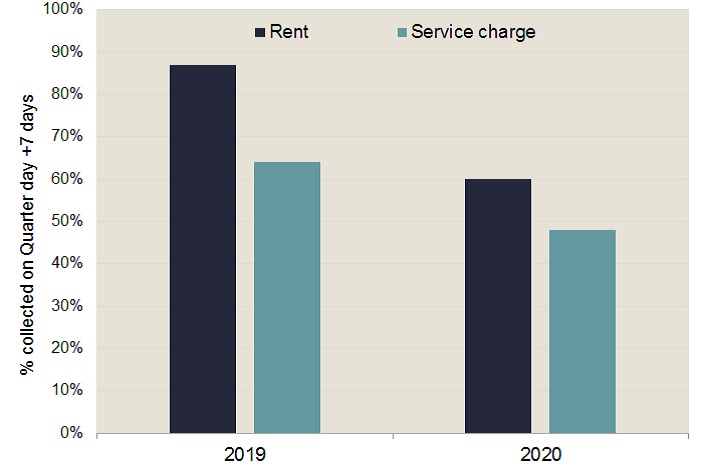
Savills also analysed what proportion of rent payments they have managed to collect over the seven days after the latest quarter day (25 March). The data shows that collectively 60% of rent was collected and approximately 48% of service charges (see chart below).
James Gulliford, joint head of UK investment at Savills, comments: ““Savills data for the properties which we manage shows the challenges that landlords are facing in collecting both rent and service charges. While the picture is overall a negative one it should be noted that even last year for the same period, with no pandemic, in the first seven days following rent day, we had only collected 87% of rents and 64% of service charges, with more gathered subsequently, so the overall impact in a few more weeks may be lessened.”